Home Guides
Bungalow Layout Changed After Booking? Refund May Be Possible

The Maharashtra Real Estate Regulatory Authority (MahaRERA) has clarified that homebuyers may seek a refund if significant disputes arise regarding changes to a property’s layout and design after booking, particularly if such changes result in the complete breakdown of the contractual relationship between the parties.
MahaRERA determined that the complainants were entitled to a refund of the total sum paid to the developer, plus interest, minus amounts paid for taxes, stamp duty, registration fees, and other statutory charges to government authorities.
The authority ordered the developer to reimburse the sum paid by the homebuyers, plus any interest, within 60 days of the order.
In its order, MahaRERA stated that the parties’ contractual relationship had “irretrievably broken down” and that neither was willing to proceed with the transaction. It stated that constraining either party to continue with the sale agreement would not serve the aims of justice or achieve the objectives of the Real Estate (Regulation and Development) Act. As a result, it determined that the complainants were entitled to seek remedies under Section 18 of the Act.
The case
The MahaRERA verdict involved homeowners who booked a property near Mumbai in July 2021 for more than ₹2 crore. In December 2021, the buyers signed a registered agreement for sale and paid around ₹50 lakh. Possession of the bungalow was expected for June 30, 2023.
However, disagreements emerged between the parties concerning alleged alterations to the bungalow’s layout and design, a reduction in its built-up area, changes to the parking configuration, and assurances given by the developer regarding compensation and restoration of parking access.
“Design changes and other changes were disclosed only shortly before execution of the agreement for sale, and they proceeded with the registration of the agreement solely on the basis of assurances extended by the developer regarding restoration of parallel parking access and compensation for the reduction in area,” the buyers informed MahaRERA.
The homebuyers opted to cancel the purchase in August 2022 due to project-related problems. According to the homeowners, the developer initially agreed to repay the full sum within 90 days, but then proposed a staggered payment schedule, delaying the refund. They further claimed that the developer issued forced demand notices and requested the execution of a cancellation deed, claiming false termination reasons, and that they refused to sign it.
Developer’s defence
In its answer to MahaRERA, the developer claimed that the homebuyer had failed to meet payment commitments under the bungalow purchase agreement. “All changes were duly disclosed, were necessitated by statutory approvals, and the complainants voluntarily executed the agreement with full knowledge of the final specifications,” the developer told MahaRERA.
The developer maintained that the complainants were bound by the provisions of the registered agreement for sale and could not contest the layout or specifications after signing the agreement.
The developer further claimed that the homeowners’ complaint about the reduction in built-up area was invalid because the agreement was based on the carpet area and plot area, with no contractual commitment about the built-up space. According to the developer, the homebuyers were attempting to raise issues outside of the scope of the agreement.
In its submission to MahaRERA, the developer asserted that all alterations to the layout and design were required by statutory requirements and authorization from competent authorities. It claimed that the alterations were legal, properly disclosed, and acceptable under the terms of the sale agreement. As a result, the developer maintained that no case of misrepresentation or breach of the RERA Act had been established.
MahaRERA’s verdict
According to the MahaRERA’s order, the record shows that arguments arose between the parties over the amended layout, parking configuration, and related promises, resulting in the rupture of the contract.
The MahaRERA stated that the respondent had agreed to cancel the transaction and refund the complainants’ funds, but the cancellation could not be completed due to disagreements over the proposed cancellation documents’ terms and recitals.
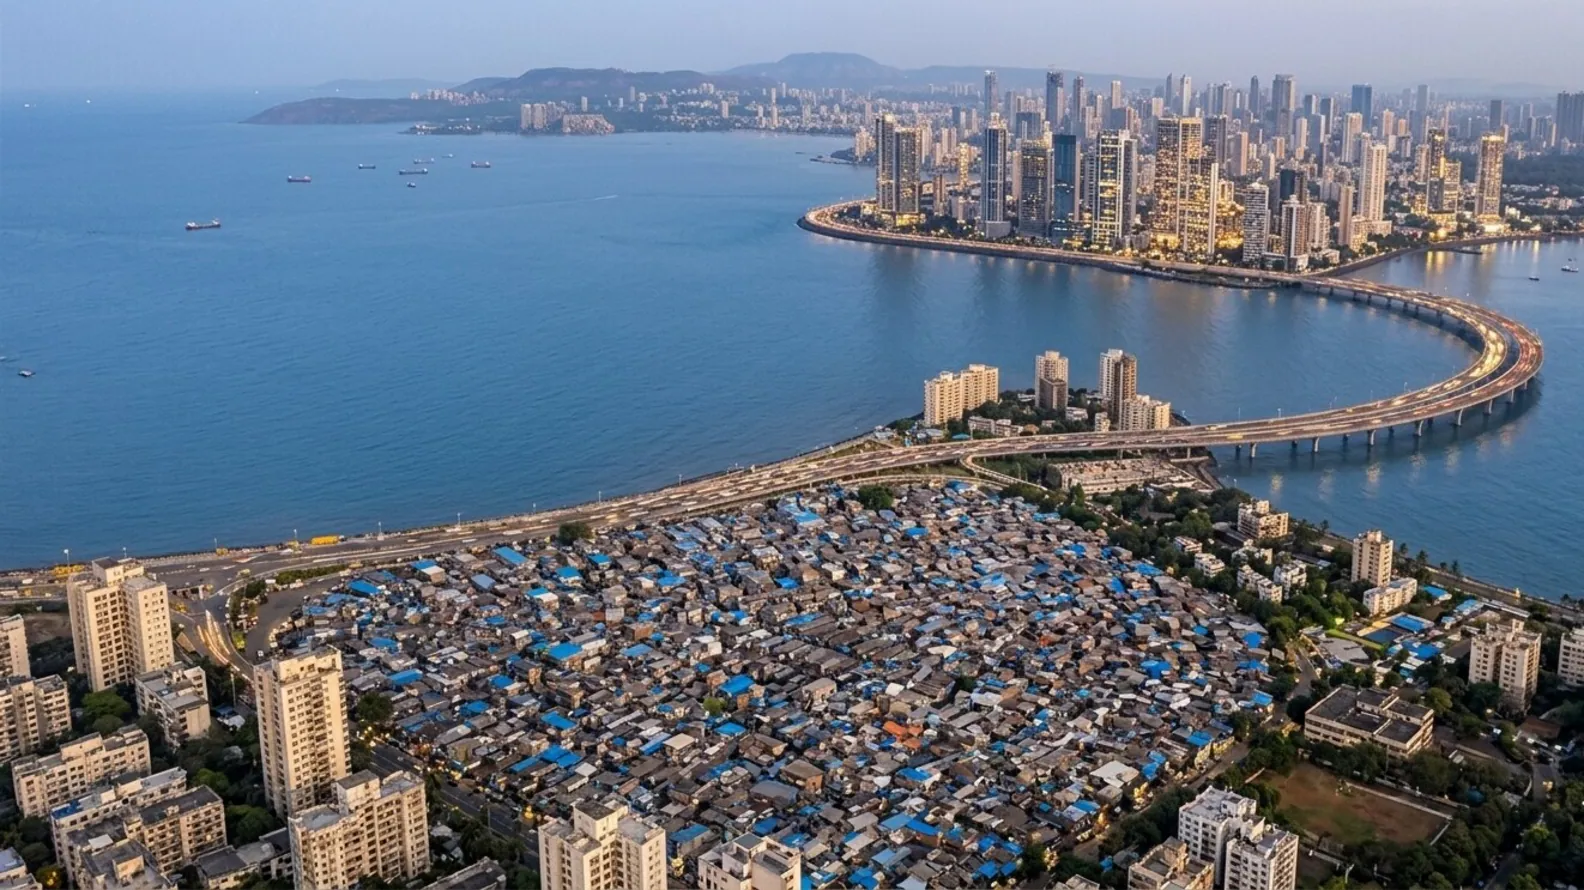
For Sagar Patil and his family, the reconstruction of their old residential building in Mumbai’s Borivali area improved their living conditions significantly, but it also resulted in a larger monthly maintenance fee. Prior to renovation, the family paid around ₹1,500 per month for their one-room kitchen flat, comprising approximately 300 sq ft, in a building over 40 years old. The structure was redeveloped approximately three months before the COVID-19 epidemic struck in 2020.
Following redevelopment, the family relocated to a one-bedroom apartment spanning 420 square feet in a modern residential complex with amenities such as a double-height lobby, an air-conditioned lobby, a podium, a gym, a swimming pool, and valet parking. The monthly maintenance price climbed to ₹5,500 due to higher costs of maintaining the facilities and managing the rebuilt property.
While the Patil family is now paying roughly four times its previous maintenance price, they are pleased with the overall results of the redevelopment. The family received a large sum from the developer, which it thinks would cover maintenance costs for the next seven to eight years.
The rehabilitation also elevated a property with minimal sales and rental potential to a more valuable asset. According to the family, the ancient apartment in the decaying building had little resale value, and finding a tenant was tough. Today, the rebuilt 1 BHK property may bring roughly ₹1.20 crore if sold, while its rental value is around ₹30,000-35,000 per month. For the family, the higher monthly cost is offset by an enhanced standard of living, more amenities, and a significant rise in the property’s marketability.
Why do maintenance costs rise?
According to real estate experts, the increase in maintenance costs following redevelopment is determined by the amenities given, the size of the building, the number of flats sharing common expenses, and the society’s facility management.
Expenses may include energy for common rooms, lifts, water pumps, fire safety systems, housekeeping, security personnel, garden and platform care, swimming pool operations, and gym maintenance. Buildings with mechanical or automated parking systems may incur additional costs for operating and maintaining the technology, as well as training workers or attendants. Air-conditioned lobbies, lavish landscaping, and larger common rooms can all boost electricity and cleaning costs. These expenses are typically ongoing, so homeowners must account for them even if they do not utilize every function in the building, according to experts.
According to Sanjay Ahuja, a real estate consultant from Mumbai’s Bandra-Khar area, having a swimming pool or heated pool can significantly reduce monthly maintenance costs in housing societies.Buildings with a hot water swimming pool will have a greater maintenance cost since it takes energy to keep the water temperature constant, in addition to the costs of filtration, cleaning, chemicals, and equipment maintenance. The extent of the rise is determined by the size of the pool, the heating technique employed, the operating hours, and the number of apartments sharing expenditures. According to Ahuja, even slight changes might boost monthly maintenance costs by ₹1 or ₹2 per square foot.
Expenses rise after a housing society is created.
Experts believe that homeowners should be aware of the shift from a developer-managed project to a residents’ society.
During the initial period after possession, the developer may give maintenance support or contribute to expenses in accordance with the provisions of the redevelopment agreement. After the society is founded and the managing committee takes over the building, residents may be responsible for the building’s operation and maintenance costs.We recommend that consumers make their final decision on a house purchase after taking into account the cost of maintenance. Monthly upkeep may be reduced in freestanding buildings, but costlier in gated communities. Before making a purchase, homebuyers should inquire about per square foot or monthly upkeep, according to Devendra Singh, a Mumbai-based real estate consultant.
Kamlesh Iyer, a Nagpur resident, reported that their housing society spent over ₹5 lakh to replace the automatic elevator doors after the developer turned over fee post-redevelopment.
“We had a few horrific occurrences where people, even small children, became trapped within the lift due to unexpected power outages, and the pure terror of being locked in a dark, solid metal box was very traumatic for them. That’s when our society decided that passenger safety and peace of mind should come first,” Iyer explained.
“We contacted a reputable elevator brand to replace the previous system with transparent glass doors in the lift. The total cost of upgrading our 8-story building is estimated to be between ₹4 and ₹5 lakhs. It was a considerable expense, and we had to ask all of the members to contribute from their own pockets, but seeing the light halls from within the cabin entirely reduces the claustrophobic sensation, and everyone feels more safer today,” said Iyer.
Mumbai’s Redevelopment Market
Since 2020, the Mumbai real estate market’s redevelopment segment has reported over 1,000 projects, accounting for 13% of the city’s total residential supply and 15% of housing sales, according to a research released on September 3 by JLL India and NAREDCO.
Five localities, including Borivali, Malad, Andheri, Vikhroli, and Goregaon, have accounted for around 36% of all projects since 2020. The western suburbs account for 35-45% of all launches and sales (2025-H1 2026).
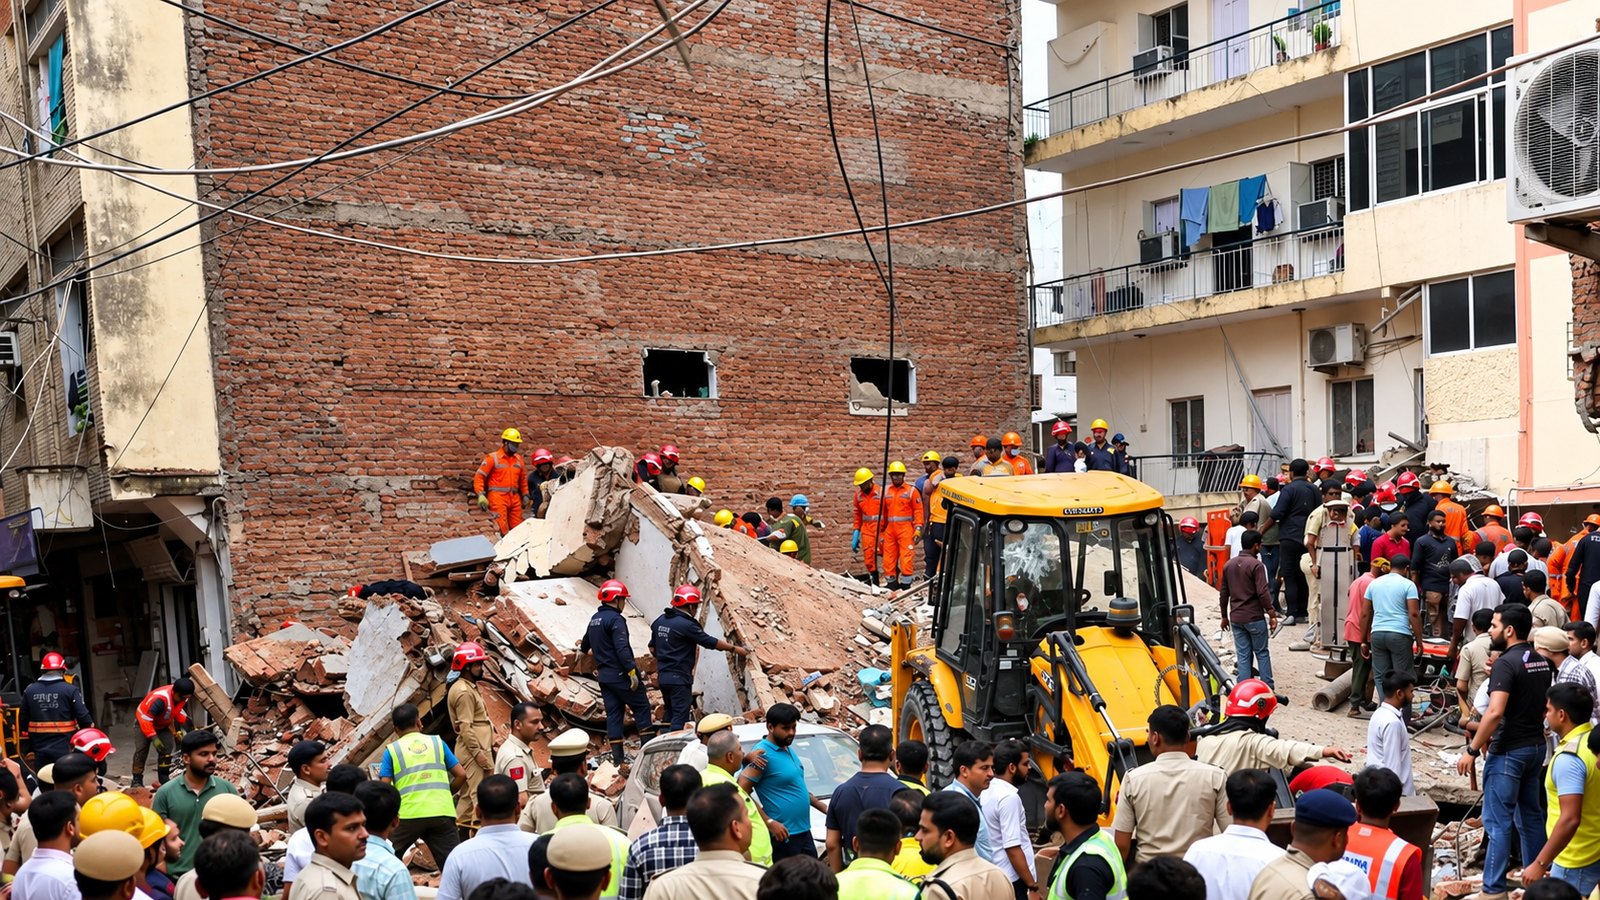
The collapse of a building in Delhi on Sunday has sparked concerns about structural safety, unauthorized construction, and the condition of the city’s aging residential buildings. The incident serves as a reminder to those who live in paying guest (PG) accommodations that checking rent, location, and amenities may not be sufficient before settling into a residence.
Tenants should also check to see if the building is legally approved and structurally sound, according to real estate professionals. Before signing a deal, renters should undertake a basic PG safety audit that looks for structural and legal red signs. This is especially relevant in older buildings in Mumbai and Delhi, where unauthorized expansions, high occupancy, and aging infrastructure all pose safety issues.
Here are 7 items you should consider while doing a PG safety audit: Structural vs. Legal Red Flags
1) Unapproved vertical extensions
Experts noted that a freshly built top floor, terrace room, or mezzanine should not be presumed to be legal. Tenants should compare the actual number of storeys to the approved building plan and completion/occupancy documentation.
The Brihanmumbai Municipal Corporation (BMC) manages the building-plan and development-permission systems in Mumbai, and certified copies of sanctioned plans, IOD, commencement, and occupation certificates can be obtained from the local Building Proposal office. In Delhi, the MCD building-approval system grants access to sanctioned-plan and completion-cum-occupancy procedures.
2) Basement excavation and water seepage
Fresh excavation, exposed foundations, chronic moisture, water accumulation, large fractures, or plaster falling from ceilings should all be seen as warning indicators. A renter should not determine structural safety based solely on paintwork. If fractures are broad or expanding, doors and windows suddenly slam, floors appear uneven, or reinforcement is revealed, tenants should inquire about the building’s structural stability report with the PG landlord.
3) Occupational Certificate or Fire NOC
Experts advise residents to request the Occupancy/Completion Certificate and relevant fire-safety certification from their PG landlord.In Delhi, fire certification regulations apply to specific categories, such as residential structures above 15 meters or ground-plus-four upper storeys, whereas hotels and guest houses above 12 meters or ground-plus-three upper storeys are covered separately. High-rise and special buildings in Mumbai require fire department certification before an occupancy certificate is issued, according to architect Madhur Ramkrishna.
4) Overcrowding and restricted emergency exits.
A PG with too many beds, locked staircases, barred halls, makeshift rooms, or grills blocking exits. Fire safety is more than just having extinguishers; escape routes must be useable and practical, according to Ramkrishna.
5) Building is older than the structural-audit threshold
Buildings in Mumbai that have been in operation for more than 30 years must be inspected by a competent structural engineer under Section 353B of the Municipal Corporation Act. After March 21, 2001, high-rise structures of 15 meters or greater in Delhi require a structural examination every 30 years, whereas those sanctioned prior to that date are subject to mandatory structural-safety audits.Tenants should confirm that the top floor shown in the approved construction design corresponds to the floor built on site. Even if an additional floor or terrace structure has power or property tax records, it may be illegal. Tenants should obtain the sanctioned plan, OC, and all required safety clearances,” said Mumbai-based architect Ashish Sawant.
Prospects for student housing
According to Colliers, industry estimates place demand for student housing at over 12 million beds, but organized co-living inventory is only around 300,000 units. Organized inventory might rise to roughly one million beds by 2030, as operators aim to tap demand from millions of students who relocate away from home each year for higher education.
Introduction
Whether you’re planning to buy your first home or already paying a home loan, one financial term you should always keep an eye on is the RBI Repo Rate. Even a small change in the repo rate can significantly affect your monthly EMI, total interest paid, and overall loan affordability.
Since most banks in India now offer repo-linked floating home loans, RBI’s monetary policy decisions directly influence millions of borrowers. Understanding how the repo rate works can help you make smarter financial decisions and save money over the life of your loan.
What is the RBI Repo Rate?
The Repo Rate is the interest rate at which the Reserve Bank of India (RBI) lends short-term funds to commercial banks.
Banks borrow money from the RBI whenever they face liquidity shortages. The RBI uses the repo rate as a monetary policy tool to:
Control inflation
Manage liquidity
Encourage or slow economic growth
Influence borrowing costs across the banking system
When the RBI changes the repo rate, banks generally adjust their lending rates accordingly.
How Does the Repo Rate Affect Home Loans?
The impact is straightforward:
When RBI Increases the Repo Rate
Banks borrow at a higher cost.
Home loan interest rates may increase.
Floating-rate loan EMIs become more expensive.
Homebuyers pay more interest over time.
When RBI Reduces the Repo Rate
Borrowing becomes cheaper for banks.
Home loan interest rates may fall.
Monthly EMIs reduce or loan tenure becomes shorter.
Buying a home becomes more affordable.
This is especially relevant for floating-rate home loans, whose interest rates are linked to external benchmarks such as the RBI repo rate.
Floating vs Fixed Home Loans
Floating Rate Home Loan
Interest changes with the RBI repo rate.
EMI or tenure can increase or decrease.
Best during falling interest-rate cycles.
Fixed Rate Home Loan
Interest remains constant for the agreed period.
EMI stays unchanged.
Offers stability but may be slightly more expensive initially.
Example: How a Repo Rate Change Impacts EMI
Suppose you have:
Loan Amount: ₹60 lakh
Loan Tenure: 20 years
Interest Rate: 8.5%
If the interest rate rises by 0.5% following a repo rate hike:
Your monthly EMI increases.
Alternatively, your lender may keep the EMI unchanged and extend the loan tenure, resulting in higher total interest over the life of the loan.
Latest RBI Repo Rate Trend
The RBI reviews the repo rate during every Monetary Policy Committee (MPC) meeting based on:
Inflation
GDP growth
Global economic conditions
Liquidity in the banking system
Changes in the repo rate are closely watched because they influence borrowing costs across sectors, including housing finance.
How Homebuyers Can Prepare
- Choose the Right Loan Type
Select a floating or fixed-rate loan based on your financial goals and market conditions.
- Make Part Prepayments
Reducing the principal lowers future interest costs.
- Maintain a Good Credit Score
A strong credit profile can help you negotiate better interest rates.
- Compare Multiple Lenders
Interest rates, processing fees, and reset periods vary between banks and housing finance companies.
- Track RBI Announcements
Knowing upcoming policy decisions helps you plan refinancing or prepayments effectively.
Who Benefits Most from a Repo Rate Cut?
A reduction in the repo rate is particularly beneficial for:
First-time homebuyers
Existing floating-rate borrowers
Buyers upgrading to larger homes
Real estate developers, as improved affordability can stimulate housing demand.
Final Thoughts
The RBI repo rate is one of the most important factors influencing home loan costs in India. While you cannot control interest rate movements, understanding how they affect your loan allows you to make better borrowing decisions.
If you’re planning to purchase a home or refinance an existing loan, keep an eye on RBI policy announcements, compare lenders, and review your repayment strategy regularly. Staying informed can reduce your borrowing costs and improve your long-term financial health.

Ranbir Kapoor Rents Pune Trump Towers Flat for ₹4.63 Lakh/Month

AI to Drive APAC Office Demand Growth

MahaRERA Recovers ₹369 Crore from Developers, Mumbai Leads

43,000 Homes Unsold in Navi Mumbai Amid Buyer Slowdown

Vijayta Raheja Applauds India’s ₹4 Lakh Crore Urban Vision at ET Maharashtra Business Summit

K Raheja & IHG Team Up to Elevate Powai’s Hospitality Landscape
-
 Real Estate News6 months ago
43,000 Homes Unsold in Navi Mumbai Amid Buyer Slowdown
-
 Real Estate News6 months ago
Vijayta Raheja Applauds India’s ₹4 Lakh Crore Urban Vision at ET Maharashtra Business Summit
-
 New Projects & Launches6 months ago
K Raheja & IHG Team Up to Elevate Powai’s Hospitality Landscape
-
 Real Estate News6 months ago
Mumbai’s Largest MHADA Redevelopment Drive Set to Transform 923 Acres
-
 NRI Real Estate7 months ago
Will NRI Investments Drive Mumbai Housing?
-
 Global Real Estate7 months ago
Spanish Youth Hostel Group Considers London Real Estate Deals
-
 NRI Real Estate7 months ago
How NRIs Are Driving India’s Property Market?
-
 Real Estate News7 months ago
John Abraham Firm Renews Bandra Rent at ₹12L/Month