Home Guides
Moving Into a PG? 5 Red Flags You Must Check Before Moving In

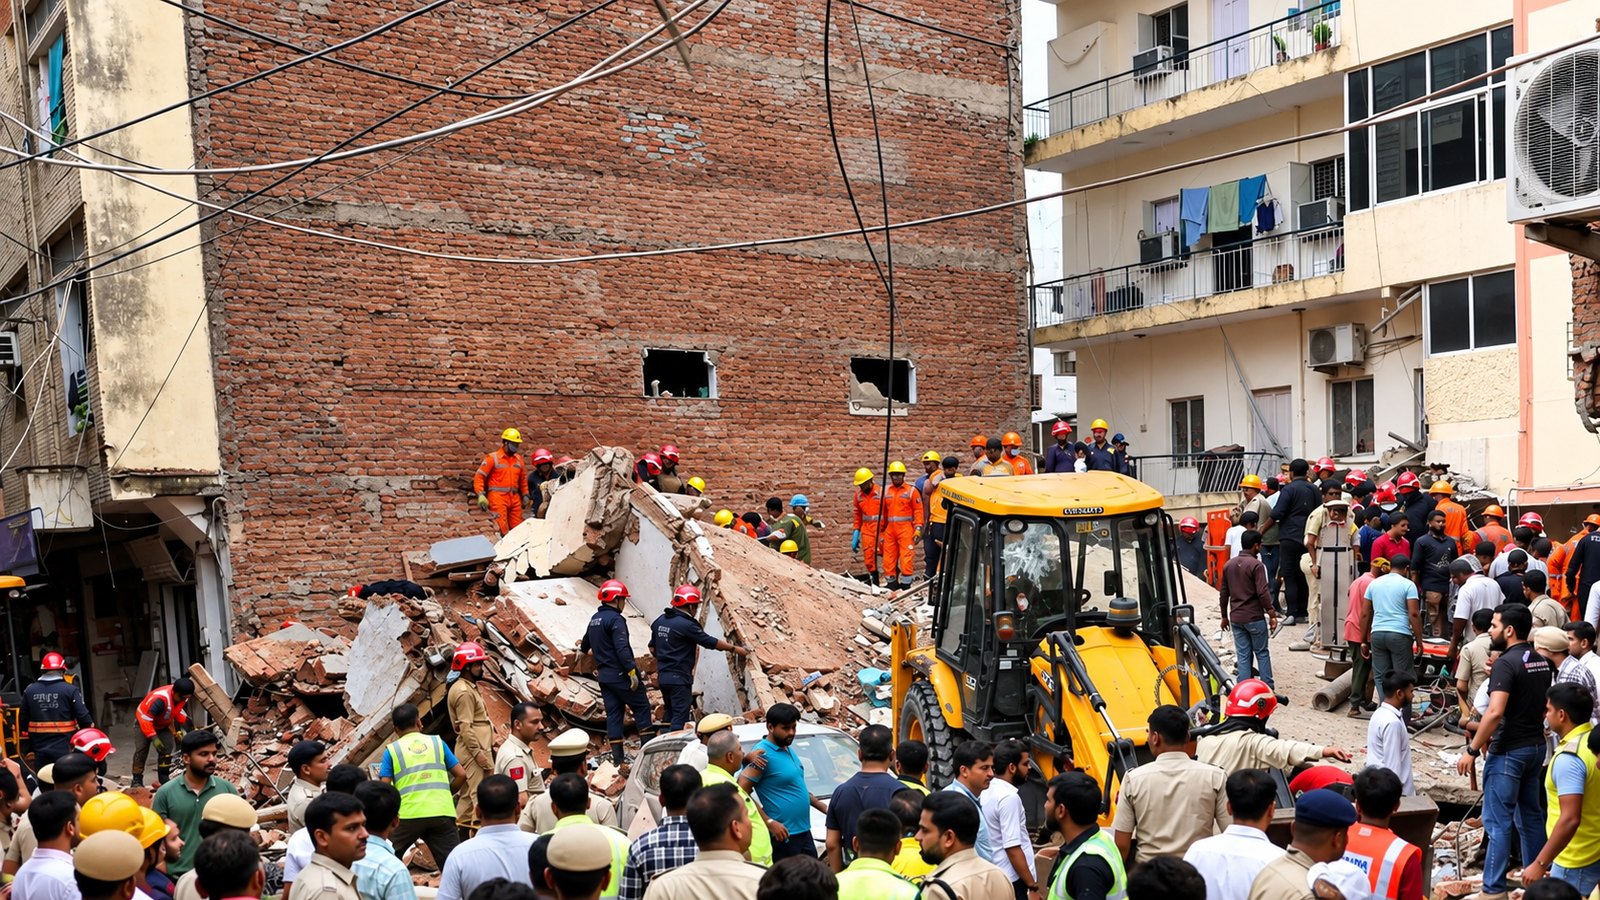
The collapse of a building in Delhi on Sunday has sparked concerns about structural safety, unauthorized construction, and the condition of the city’s aging residential buildings. The incident serves as a reminder to those who live in paying guest (PG) accommodations that checking rent, location, and amenities may not be sufficient before settling into a residence.
Tenants should also check to see if the building is legally approved and structurally sound, according to real estate professionals. Before signing a deal, renters should undertake a basic PG safety audit that looks for structural and legal red signs. This is especially relevant in older buildings in Mumbai and Delhi, where unauthorized expansions, high occupancy, and aging infrastructure all pose safety issues.
Here are 7 items you should consider while doing a PG safety audit: Structural vs. Legal Red Flags
1) Unapproved vertical extensions
Experts noted that a freshly built top floor, terrace room, or mezzanine should not be presumed to be legal. Tenants should compare the actual number of storeys to the approved building plan and completion/occupancy documentation.
The Brihanmumbai Municipal Corporation (BMC) manages the building-plan and development-permission systems in Mumbai, and certified copies of sanctioned plans, IOD, commencement, and occupation certificates can be obtained from the local Building Proposal office. In Delhi, the MCD building-approval system grants access to sanctioned-plan and completion-cum-occupancy procedures.
2) Basement excavation and water seepage
Fresh excavation, exposed foundations, chronic moisture, water accumulation, large fractures, or plaster falling from ceilings should all be seen as warning indicators. A renter should not determine structural safety based solely on paintwork. If fractures are broad or expanding, doors and windows suddenly slam, floors appear uneven, or reinforcement is revealed, tenants should inquire about the building’s structural stability report with the PG landlord.
3) Occupational Certificate or Fire NOC
Experts advise residents to request the Occupancy/Completion Certificate and relevant fire-safety certification from their PG landlord.In Delhi, fire certification regulations apply to specific categories, such as residential structures above 15 meters or ground-plus-four upper storeys, whereas hotels and guest houses above 12 meters or ground-plus-three upper storeys are covered separately. High-rise and special buildings in Mumbai require fire department certification before an occupancy certificate is issued, according to architect Madhur Ramkrishna.
4) Overcrowding and restricted emergency exits.
A PG with too many beds, locked staircases, barred halls, makeshift rooms, or grills blocking exits. Fire safety is more than just having extinguishers; escape routes must be useable and practical, according to Ramkrishna.
5) Building is older than the structural-audit threshold
Buildings in Mumbai that have been in operation for more than 30 years must be inspected by a competent structural engineer under Section 353B of the Municipal Corporation Act. After March 21, 2001, high-rise structures of 15 meters or greater in Delhi require a structural examination every 30 years, whereas those sanctioned prior to that date are subject to mandatory structural-safety audits.Tenants should confirm that the top floor shown in the approved construction design corresponds to the floor built on site. Even if an additional floor or terrace structure has power or property tax records, it may be illegal. Tenants should obtain the sanctioned plan, OC, and all required safety clearances,” said Mumbai-based architect Ashish Sawant.
Prospects for student housing
According to Colliers, industry estimates place demand for student housing at over 12 million beds, but organized co-living inventory is only around 300,000 units. Organized inventory might rise to roughly one million beds by 2030, as operators aim to tap demand from millions of students who relocate away from home each year for higher education.
Introduction
Whether you’re planning to buy your first home or already paying a home loan, one financial term you should always keep an eye on is the RBI Repo Rate. Even a small change in the repo rate can significantly affect your monthly EMI, total interest paid, and overall loan affordability.
Since most banks in India now offer repo-linked floating home loans, RBI’s monetary policy decisions directly influence millions of borrowers. Understanding how the repo rate works can help you make smarter financial decisions and save money over the life of your loan.
What is the RBI Repo Rate?
The Repo Rate is the interest rate at which the Reserve Bank of India (RBI) lends short-term funds to commercial banks.
Banks borrow money from the RBI whenever they face liquidity shortages. The RBI uses the repo rate as a monetary policy tool to:
Control inflation
Manage liquidity
Encourage or slow economic growth
Influence borrowing costs across the banking system
When the RBI changes the repo rate, banks generally adjust their lending rates accordingly.
How Does the Repo Rate Affect Home Loans?
The impact is straightforward:
When RBI Increases the Repo Rate
Banks borrow at a higher cost.
Home loan interest rates may increase.
Floating-rate loan EMIs become more expensive.
Homebuyers pay more interest over time.
When RBI Reduces the Repo Rate
Borrowing becomes cheaper for banks.
Home loan interest rates may fall.
Monthly EMIs reduce or loan tenure becomes shorter.
Buying a home becomes more affordable.
This is especially relevant for floating-rate home loans, whose interest rates are linked to external benchmarks such as the RBI repo rate.
Floating vs Fixed Home Loans
Floating Rate Home Loan
Interest changes with the RBI repo rate.
EMI or tenure can increase or decrease.
Best during falling interest-rate cycles.
Fixed Rate Home Loan
Interest remains constant for the agreed period.
EMI stays unchanged.
Offers stability but may be slightly more expensive initially.
Example: How a Repo Rate Change Impacts EMI
Suppose you have:
Loan Amount: ₹60 lakh
Loan Tenure: 20 years
Interest Rate: 8.5%
If the interest rate rises by 0.5% following a repo rate hike:
Your monthly EMI increases.
Alternatively, your lender may keep the EMI unchanged and extend the loan tenure, resulting in higher total interest over the life of the loan.
Latest RBI Repo Rate Trend
The RBI reviews the repo rate during every Monetary Policy Committee (MPC) meeting based on:
Inflation
GDP growth
Global economic conditions
Liquidity in the banking system
Changes in the repo rate are closely watched because they influence borrowing costs across sectors, including housing finance.
How Homebuyers Can Prepare
- Choose the Right Loan Type
Select a floating or fixed-rate loan based on your financial goals and market conditions.
- Make Part Prepayments
Reducing the principal lowers future interest costs.
- Maintain a Good Credit Score
A strong credit profile can help you negotiate better interest rates.
- Compare Multiple Lenders
Interest rates, processing fees, and reset periods vary between banks and housing finance companies.
- Track RBI Announcements
Knowing upcoming policy decisions helps you plan refinancing or prepayments effectively.
Who Benefits Most from a Repo Rate Cut?
A reduction in the repo rate is particularly beneficial for:
First-time homebuyers
Existing floating-rate borrowers
Buyers upgrading to larger homes
Real estate developers, as improved affordability can stimulate housing demand.
Final Thoughts
The RBI repo rate is one of the most important factors influencing home loan costs in India. While you cannot control interest rate movements, understanding how they affect your loan allows you to make better borrowing decisions.
If you’re planning to purchase a home or refinance an existing loan, keep an eye on RBI policy announcements, compare lenders, and review your repayment strategy regularly. Staying informed can reduce your borrowing costs and improve your long-term financial health.
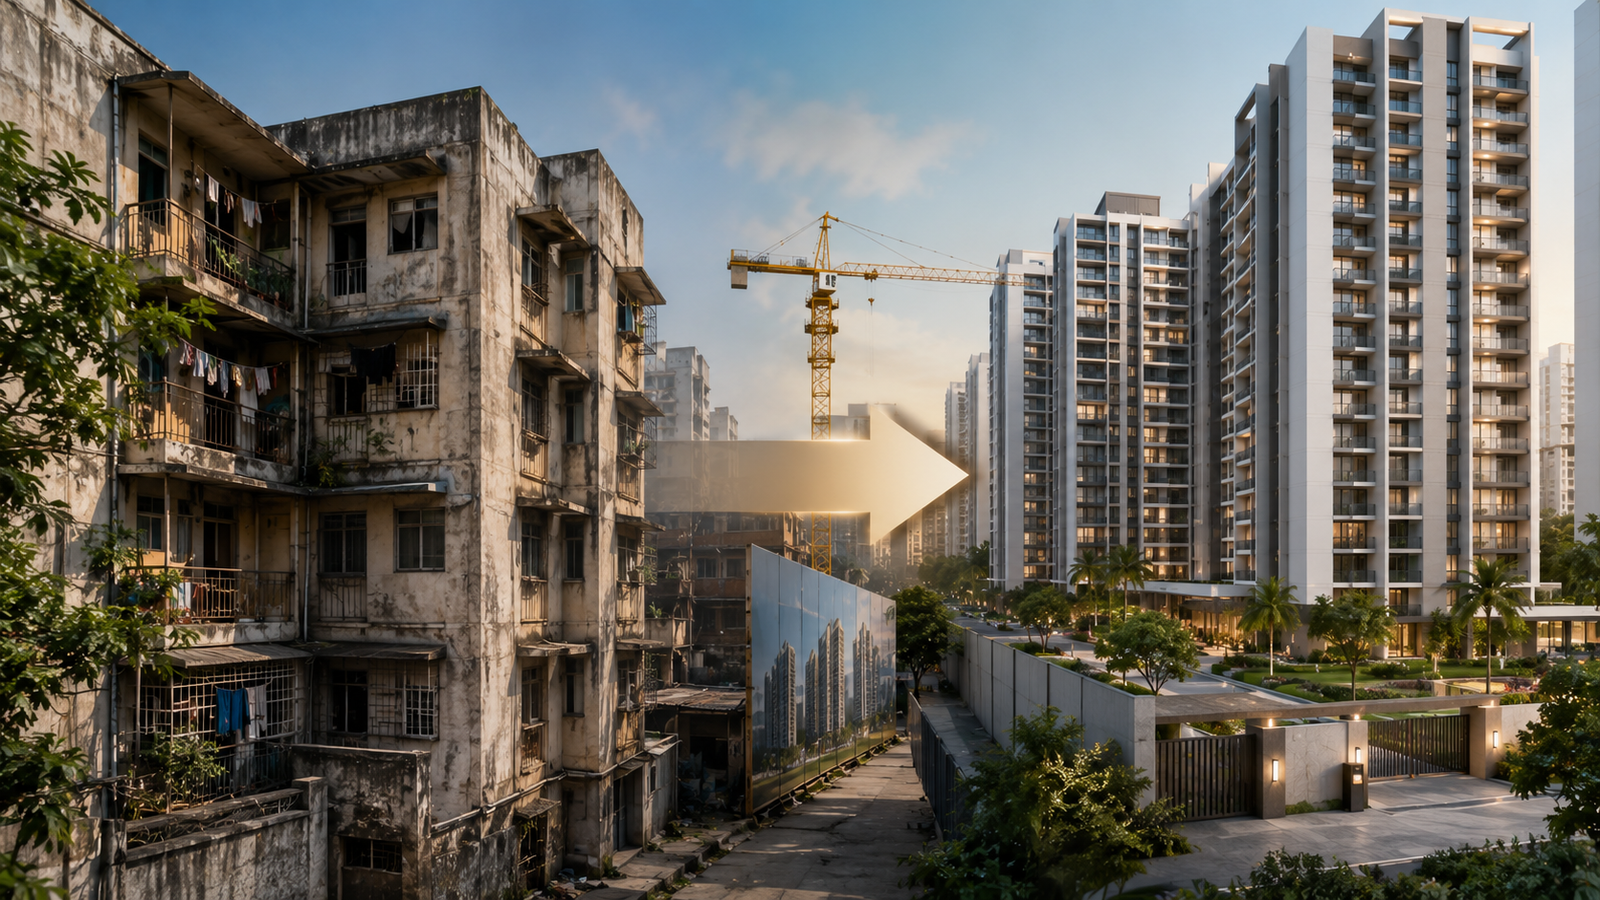
Would you buy a compact apartment today if it meant owning a much larger home a few years later? As redevelopment gathers pace in cities such as Mumbai and Pune, an increasing number of homebuyers are betting on ageing housing societies instead of brand-new projects. The attraction is compelling: buy an older flat at a lower price, receive a larger apartment after redevelopment, and potentially unlock significant value without paying current market prices for a bigger home.
Shirish Tandel (name changed) has a budget of ₹1 crore, but finding a spacious 2 BHK in his preferred locality in Pune has proved difficult. A 750 sq ft apartment there costs around ₹1.40 crore, well beyond his budget.
During his search, Tandel came across an alternative: a 500 sq ft 1 BHK with a 200 sq ft balcony, priced at ₹92 lakh, in a housing society slated for redevelopment next year. The society has already signed a development agreement (DA) with the developer.
Under the redevelopment plan, the existing flat would be upgraded to a 745 sq ft 2 BHK. Tandel also intends to purchase an additional 200 sq ft from the developer at the prevailing rate of ₹10,000–11,000 per sq ft, allowing him to eventually own a nearly 1,000 sq ft 3 BHK.
His other option is a ready-to-move-in 590 sq ft 2 BHK priced at ₹95 lakh. However, he believes the apartment would be too small for his family of four in the long run. Rather than stretching his finances to buy a ₹1.40 crore home today, Tandel is considering the redevelopment property, which could give him a significantly larger apartment for a total investment of about ₹1.2 crore.
The trade-off is time. He is unlikely to receive possession of the redeveloped 3 BHK for another three to five years. During the redevelopment period, once residents vacate the building, the developer will pay monthly rent to homeowners. Tandel plans to use this rental compensation to cover the rent of temporary accommodation until his new home is ready.
Should homebuyers purchase an apartment in an old building?
Property consultants say redevelopment projects can make financial sense, particularly in land-constrained cities such as Mumbai and Pune, where buying a larger apartment in an established locality may otherwise be unaffordable.
However, experts suggest that prospective buyers should thoroughly verify the redevelopment agreement, approvals, the developer’s financial strength and track record, timelines for completion, corpus and rental compensation, and whether the society has obtained the required consent from members.
Developers say opportunity is lucrative, but homebuyers must remain cautious
But the strategy is not without risks. Redevelopment projects are often delayed by approvals, funding constraints, legal disputes and disagreements within housing societies. While some buyers emerge with substantially larger homes and handsome capital appreciation, others can find themselves waiting years beyond the promised completion date. Before buying into a redevelopment project, it is essential to understand the legal, financial and practical considerations that could determine whether the investment pays off.
According to real estate developers, while purchasing an old apartment in a building slated for redevelopment is a lucrative opportunity, homebuyers must remain cautious and do their homework.
“Buying an apartment in the redevelopment-going building is a good investment in the long run, but homebuyers must exercise caution and do their homework before going ahead and not just look at the purchase price,” said Anuj Mehta, Director, Dhuleva Group.
“In some of Mumbai’s mature micro-markets, large-scale redevelopment projects have fetched returns of 20-40% during the project life cycle owing to better infrastructure, facilities, and building features. But the returns depend on certain parameters that need to be checked. Homebuyers must evaluate the builder’s financial strength and experience, the status of approvals from authorities, the project completion timelines, and the redevelopment agreement to finalise their decision,” Mehta said.
According to Ram Raheja, Managing Director, S Raheja, homebuyers should carefully assess two key risks before purchasing an apartment in a building slated for redevelopment.
“First, evaluate the redevelopment timeline, as such projects depend on regulatory approvals and adequate funding. A developer with limited financial strength is more likely to face delays. Buyers should assess the developer’s execution track record rather than relying on projects in the pipeline. Second, scrutinise the society’s paperwork, including the title, members’ consent and the development agreement. Internal disputes within the society are often the biggest hidden risk and the most difficult to resolve,” Raheja said.
Mumbai redevelopment: Numbers tell the story
Mumbai’s redevelopment market continued to gather pace in 2025, with the number of redevelopment agreements rising 16% year-on-year, reflecting growing momentum in the transformation of the city’s ageing housing stock. According to Knight Frank India, 229 development agreements (DAs) for the redevelopment of old buildings were signed in 2025, compared with 196 in 2024.
The trend has continued into 2026. Nearly 70 redevelopment agreements, around 30% of the total signed in 2025, were executed in the first 74 days of the year, up to March 15, according to Knight Frank India. Overall, 1,094 redevelopment agreements were signed between January 2020 and March 15, 2026, unlocking approximately 432 acres of land for redevelopment across Mumbai.
Every year, many homebuyers postpone property visits during the monsoon, assuming it’s better to wait for clear skies. However, experienced buyers and real estate experts often do the opposite—they inspect homes during the rainy season.
Buying a property during the monsoon offers a realistic picture of its quality, construction, and surrounding infrastructure. If a home performs well in heavy rains, it’s more likely to remain comfortable and durable throughout the year.
Why Monsoon is the Smartest Time to Buy a Home
- Check for Water Leakage and Dampness
The monsoon exposes issues that remain hidden during dry weather.
Look for:
Water seepage on walls and ceilings
Damp patches
Leaking balconies and terraces
Moisture around windows and doors
These signs can save buyers from expensive repairs after possession.
- Assess Drainage Around the Property
Heavy rainfall is the perfect opportunity to evaluate drainage systems.
Check whether:
Water accumulates near entrances
Parking areas flood
Roads outside remain accessible
Society drains function properly
Good drainage is a strong indicator of quality planning.
- Understand the Local Infrastructure
Rain reveals how well an area is equipped to handle adverse weather.
Observe:
Traffic congestion
Waterlogging on roads
Public transport accessibility
Condition of nearby streets
A location that functions smoothly during heavy rains generally offers better long-term livability.
- Inspect Construction Quality
Monsoon weather puts a building’s construction standards to the test.
Pay attention to:
Cracks in walls
Roof waterproofing
Basement leakage
Exterior finishing
These issues are much easier to identify during active rainfall.
- Evaluate Natural Ventilation and Lighting
Cloudy weather helps buyers understand how much natural light enters the home.
Check:
Cross ventilation
Indoor humidity
Room brightness without artificial lighting
Well-designed homes remain airy and comfortable even during the rainy season.
- Test Society Amenities
Rain can affect common facilities significantly.
Inspect:
Clubhouse roofs
Basement parking
Children’s play area
Walking tracks
Lift lobbies and common passages
A well-maintained society continues to operate efficiently despite heavy rainfall.
- Better Negotiation Opportunities
The monsoon is traditionally a slower season for property transactions.
Buyers may benefit from:
Better pricing
Flexible payment plans
Festival offers
Additional discounts from developers
This can improve overall value for money.
Monsoon Home Inspection Checklist
Before finalizing your purchase, inspect:
✔️ Roof and ceiling for leaks
✔️ Walls for seepage and dampness
✔️ Balcony drainage
✔️ Window sealing
✔️ Basement parking
✔️ Society drainage system
✔️ Road connectivity during rains
✔️ Waterlogging in surrounding areas
✔️ Power backup availability
✔️ Elevators and common area maintenance
Expert Tip
Visit the property during or immediately after heavy rainfall instead of relying solely on brochures or virtual tours. Real-world conditions reveal the true quality of construction and neighbourhood infrastructure.
Conclusion
The monsoon offers one of the best opportunities to evaluate a property’s structural integrity, location, and long-term livability. While many buyers avoid site visits during the rains, informed homebuyers use the season to uncover hidden issues and negotiate better deals.
In real estate, a home that withstands the monsoon is often a home built to last.

Red-Light to High-Rises: Kamathipura Redevelopment

BMC OC Amnesty: Key Documents Needed

Moving Into a PG? 5 Red Flags You Must Check Before Moving In

43,000 Homes Unsold in Navi Mumbai Amid Buyer Slowdown

Vijayta Raheja Applauds India’s ₹4 Lakh Crore Urban Vision at ET Maharashtra Business Summit

K Raheja & IHG Team Up to Elevate Powai’s Hospitality Landscape
-
 Real Estate News6 months ago
43,000 Homes Unsold in Navi Mumbai Amid Buyer Slowdown
-
 Real Estate News6 months ago
Vijayta Raheja Applauds India’s ₹4 Lakh Crore Urban Vision at ET Maharashtra Business Summit
-
 New Projects & Launches6 months ago
K Raheja & IHG Team Up to Elevate Powai’s Hospitality Landscape
-
 Real Estate News6 months ago
Mumbai’s Largest MHADA Redevelopment Drive Set to Transform 923 Acres
-
 NRI Real Estate6 months ago
Will NRI Investments Drive Mumbai Housing?
-
 Global Real Estate6 months ago
Spanish Youth Hostel Group Considers London Real Estate Deals
-
 NRI Real Estate6 months ago
How NRIs Are Driving India’s Property Market?
-
 Real Estate News6 months ago
John Abraham Firm Renews Bandra Rent at ₹12L/Month